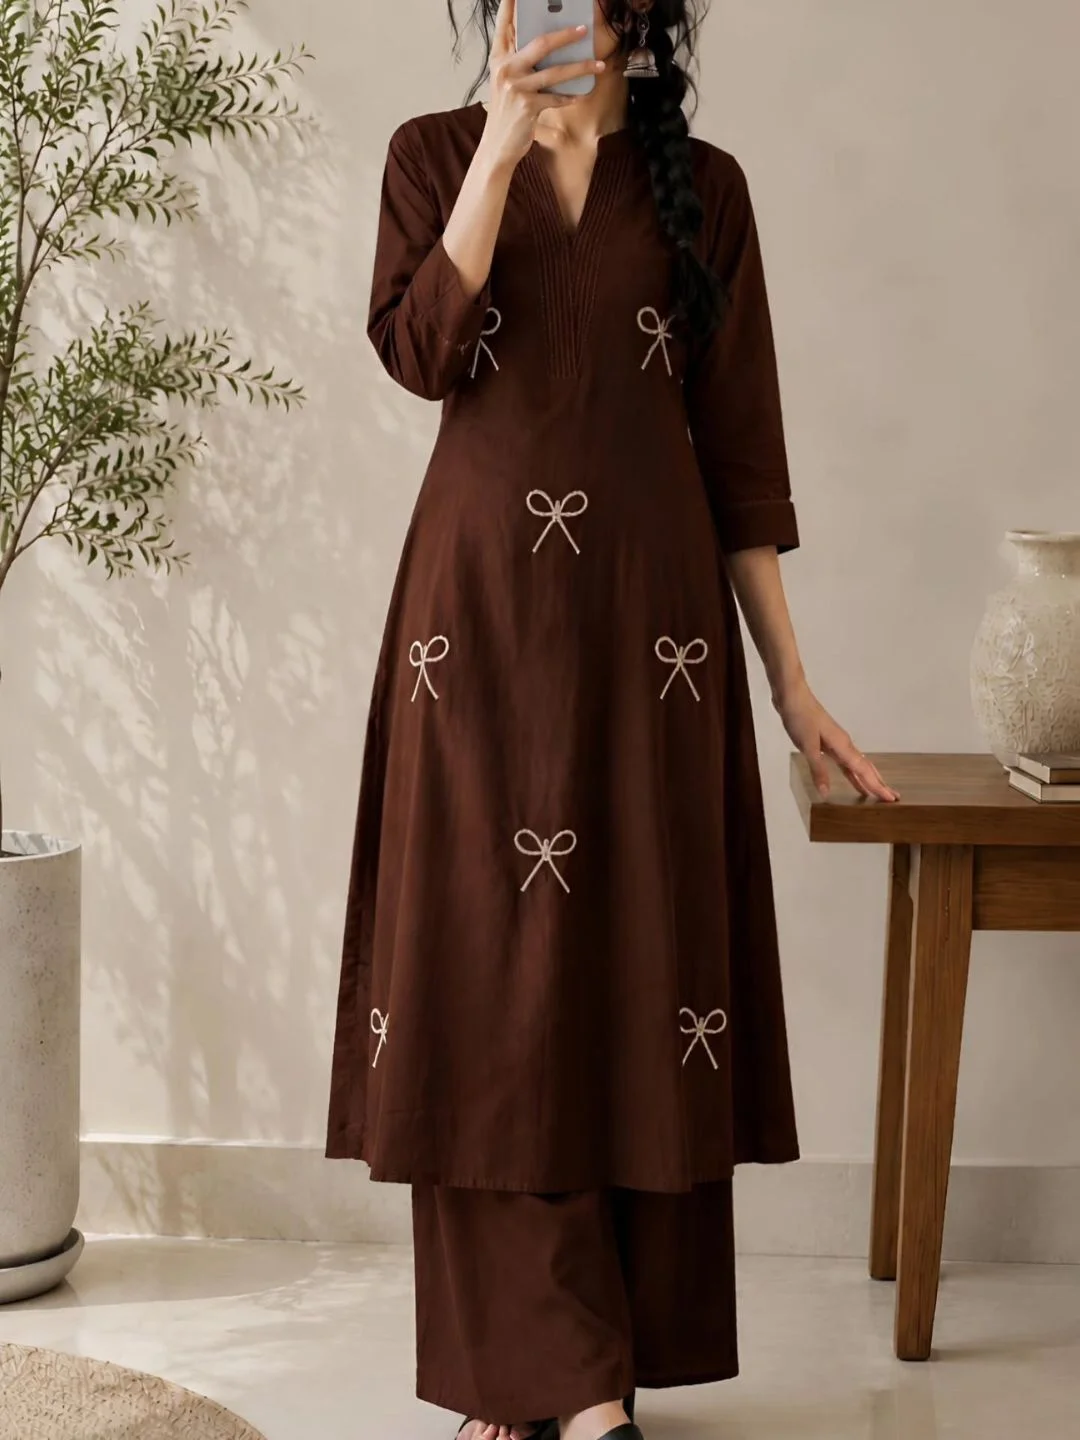
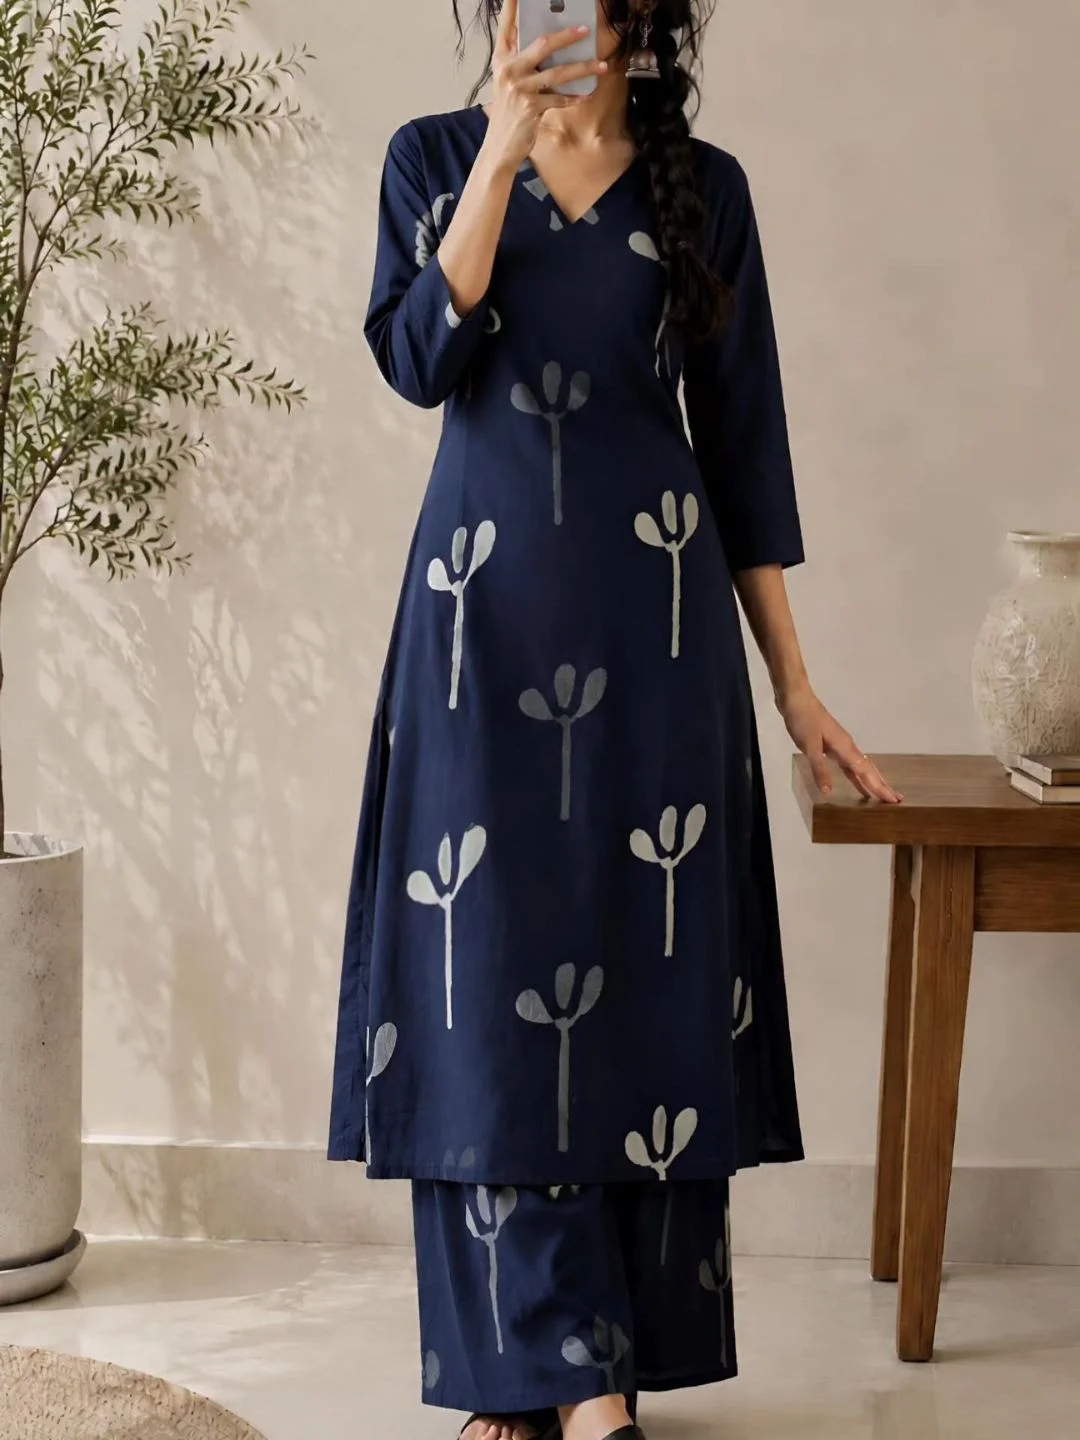
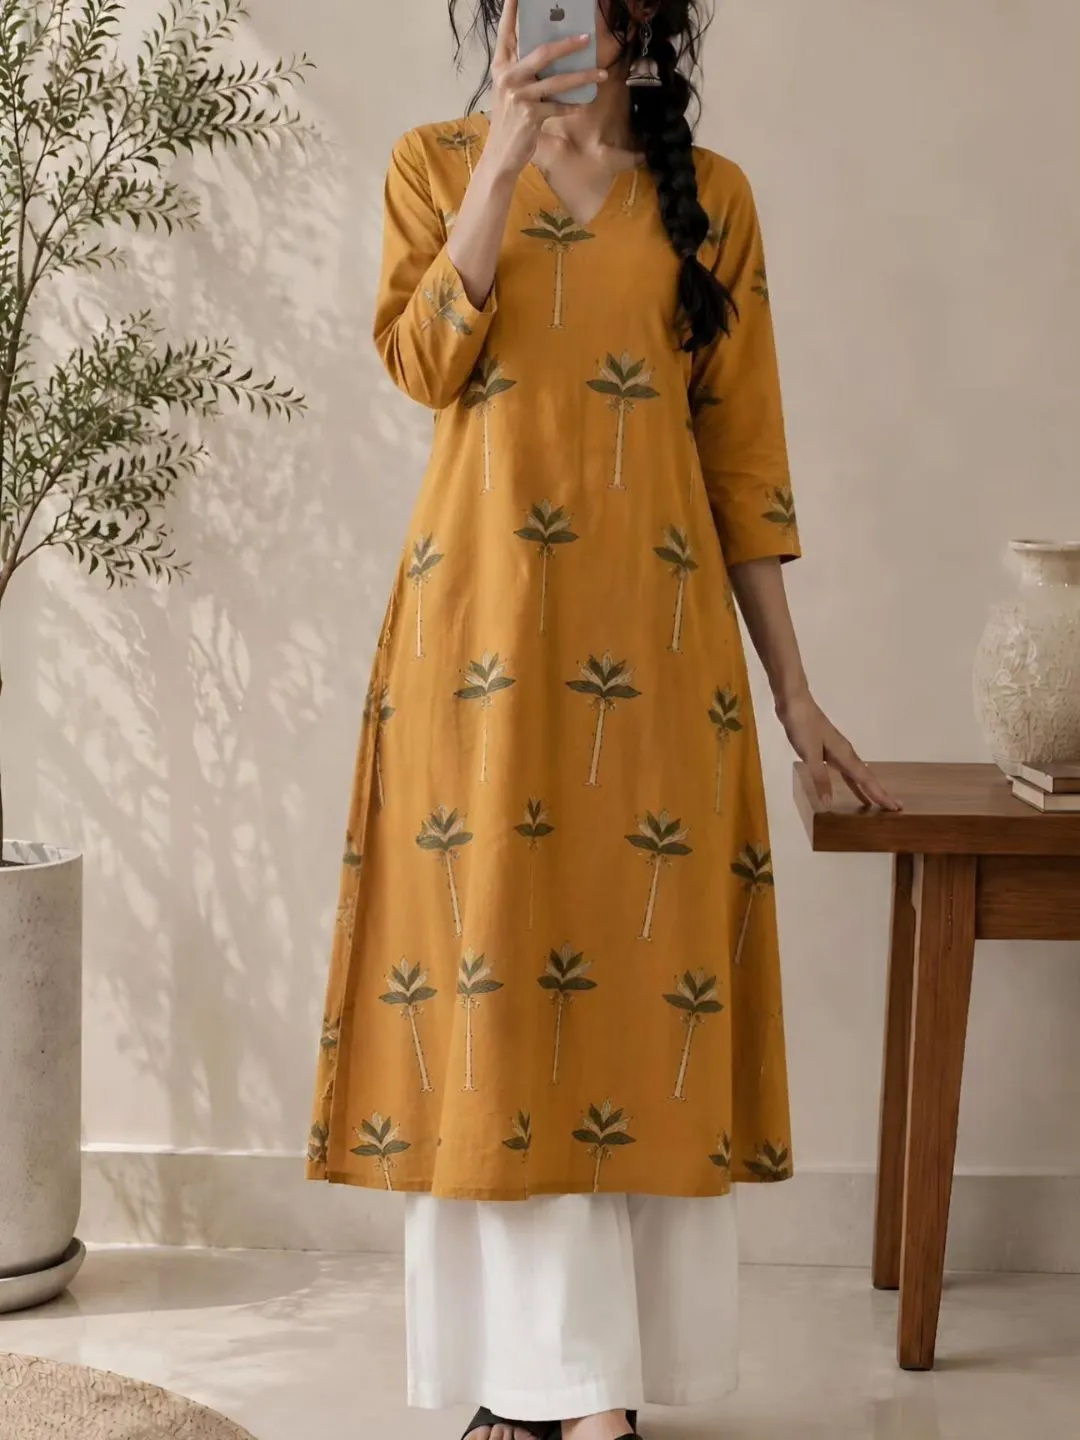
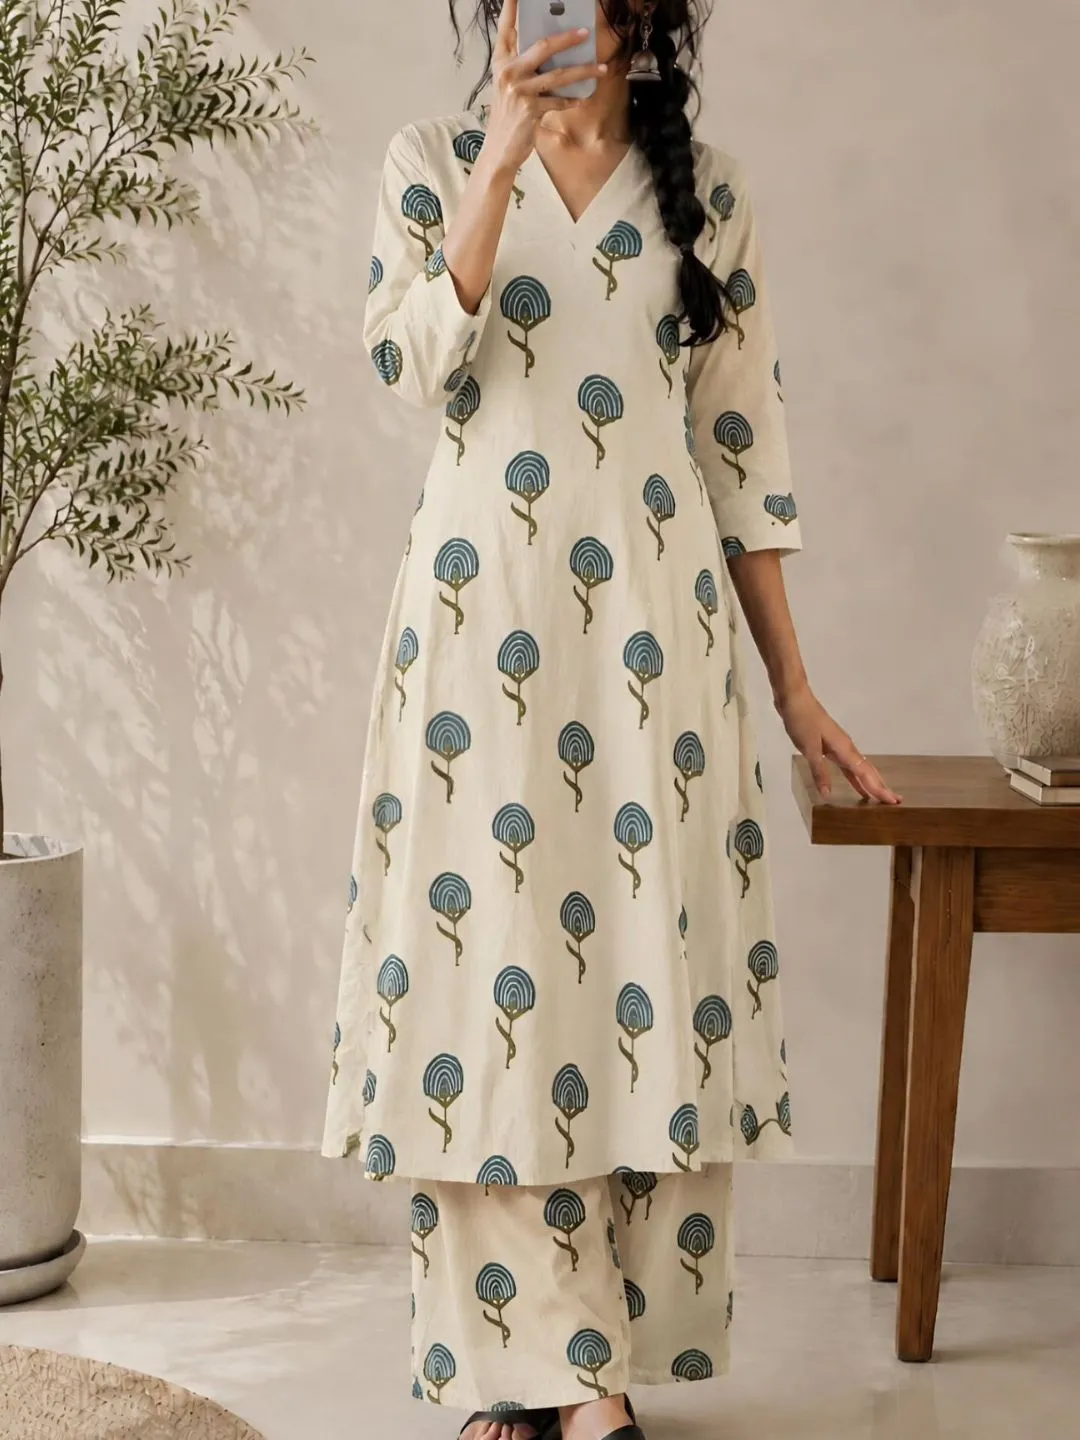
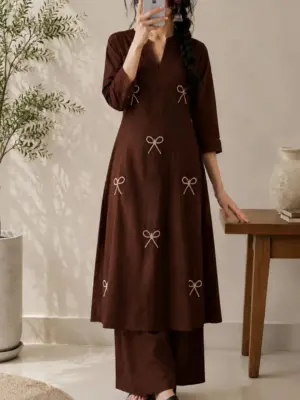
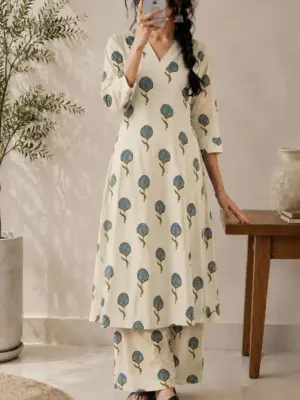
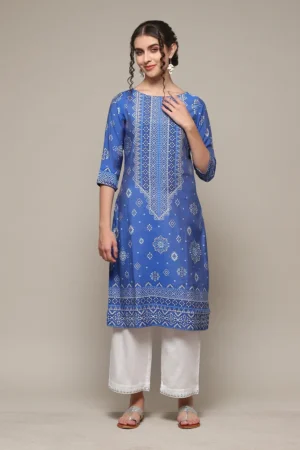
Three-Quarter Sleeve Embroidered Bow Motif Kurta with Matching Palazzo Trousers Set
Original price was: ₹699.00.₹119.00Current price is: ₹119.00.
Cash on Delivery Available | Limited Stock | Trending Style
Product Details
- Product Type: Kurta & Palazzo Combo
- Color: Rich Chocolate Brown
- Sleeves: Three-Quarter Sleeves
- Fit Type: Straight-Fit Kurta with Wide-Leg Palazzo
- Neckline: Pleated V-Neck
- Fabric: Premium Cotton Blend
- Pattern: Minimalist Embroidered Bow Motifs
- Style: Ethnic Fusion / Sophisticated Minimalist
- Occasion: Daily Wear, Office, Festive Gatherings, Brunch Dates, Cultural Events
Elevate your refined ethnic wardrobe with this exceptionally sophisticated and meticulously coordinated two-piece outfit, featuring a straight-fit chocolate brown kurta detailed with charming, minimalist embroidered bow motifs and a stylish pleated V-neckline, paired seamlessly with matching wide-leg palazzo trousers.
Buying health insurance for senior citizens after retirement is a completely different ballgame compared to buying it in your 30s, and pretending otherwise is where most families go wrong. Insurers price these policies based on age-related risk, so premiums are naturally higher, and a lot of plans come loaded with conditions that catch people off guard if they don’t read carefully before signing.
Co-payment clauses are probably the biggest surprise for first-time buyers. Many senior citizen policies require you to pay a fixed percentage of every claim out of pocket, sometimes 10-20%, regardless of how large the sum insured is. It’s the insurer’s way of managing risk on an age group that statistically files more claims, but it also means your actual out-of-pocket cost during a hospitalization can be higher than expected even with a solid policy in place.
Waiting periods are the other thing to watch closely. Most conditions common in older age, like cataracts, joint replacements, or pre-existing illnesses such as diabetes and hypertension, come with a waiting period before they’re covered, sometimes stretching to two or three years. If your parents already have a pre-existing condition, buying the policy earlier rather than later reduces how long that waiting period actually delays real coverage.
Pre-policy medical checkups are usually mandatory for senior citizen health insurance, and this actually works in your favor even though it feels like a hassle. It gives you a clear picture of existing health issues, and it means the insurer can’t reject a claim later citing an undisclosed condition, since the checkup already put everything on record. Always disclose every existing condition honestly on the proposal form, because non-disclosure is one of the most common reasons claims get rejected at the worst possible time.
Look closely at the cashless claim network too. A policy that looks cheap on paper isn’t much use if none of the good hospitals in your city are part of the insurer’s cashless network, forcing you to pay upfront and file for reimbursement later, which is exactly the kind of cash-flow stress you’re trying to avoid with insurance in the first place. Restoration benefit, where the sum insured resets after being exhausted in a policy year, is also worth prioritizing, since a single major hospitalization can otherwise leave your parents without cover for the rest of the year.
| Size | 3XL, 4XL, L, M, S, XL, XS, XXL |
|---|
Leaving Comments
Leave a Comment
Related products
Sarees
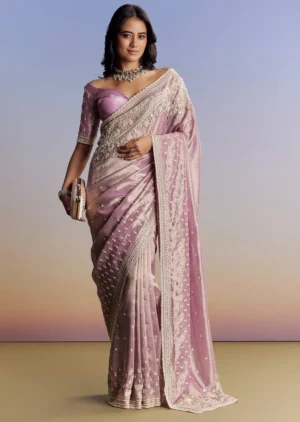
Midnight Reserve Organza Tissue Saree with Sequin & Cutdana Embroidery – Elite Glamour Portfolio
Reviews
There are no reviews yet.