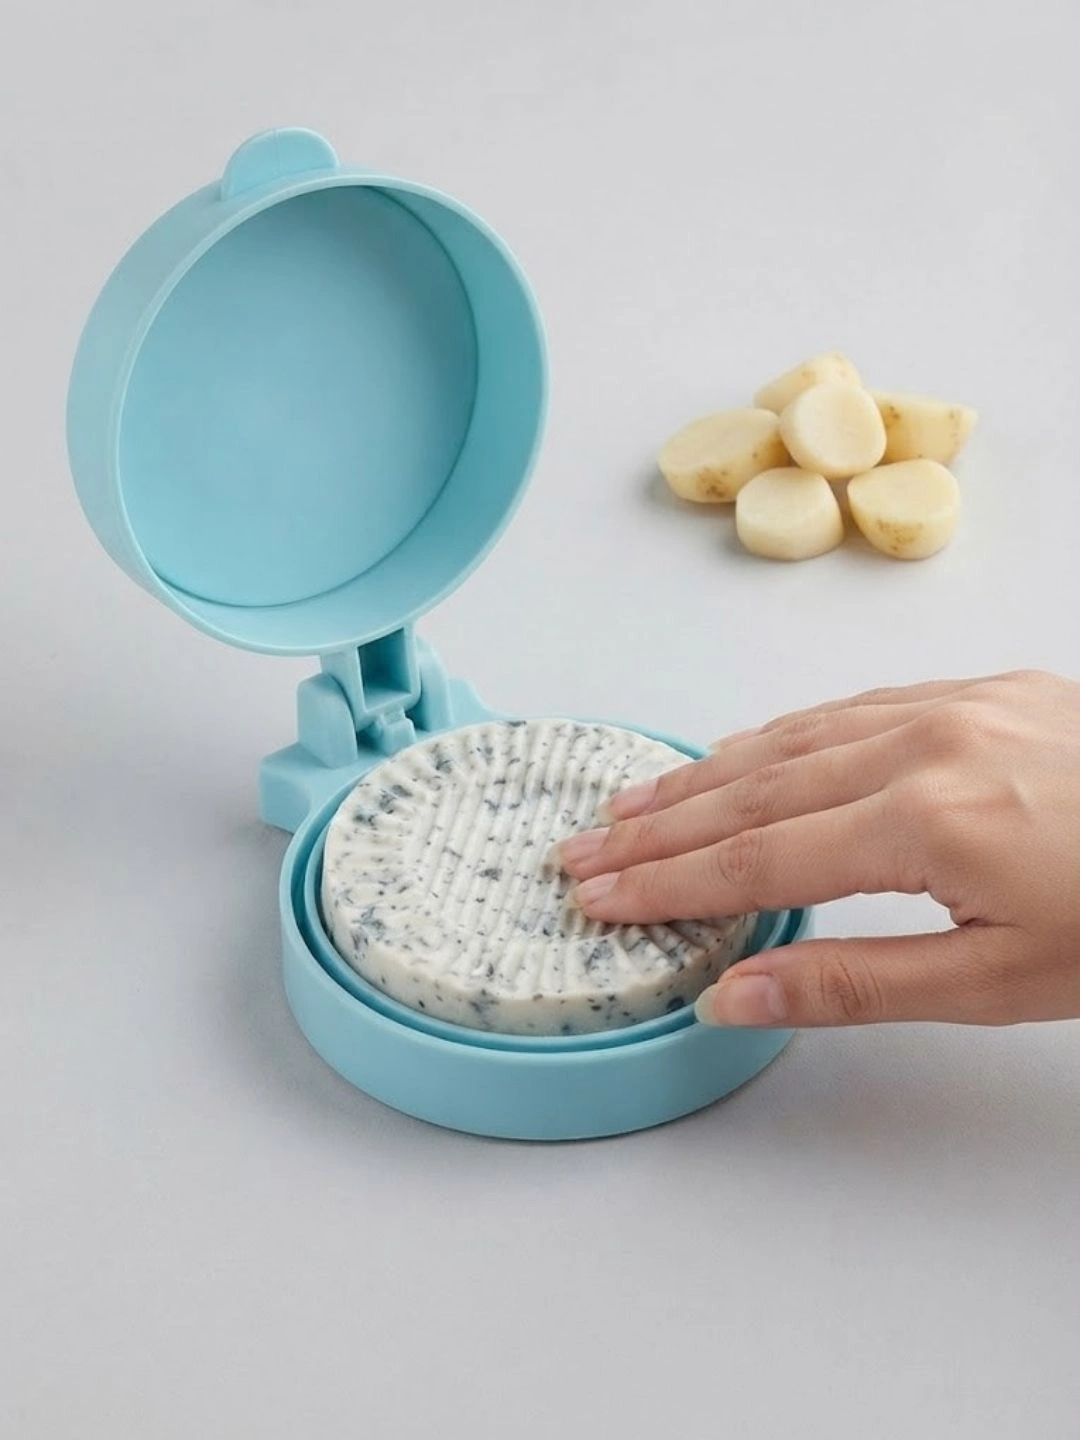
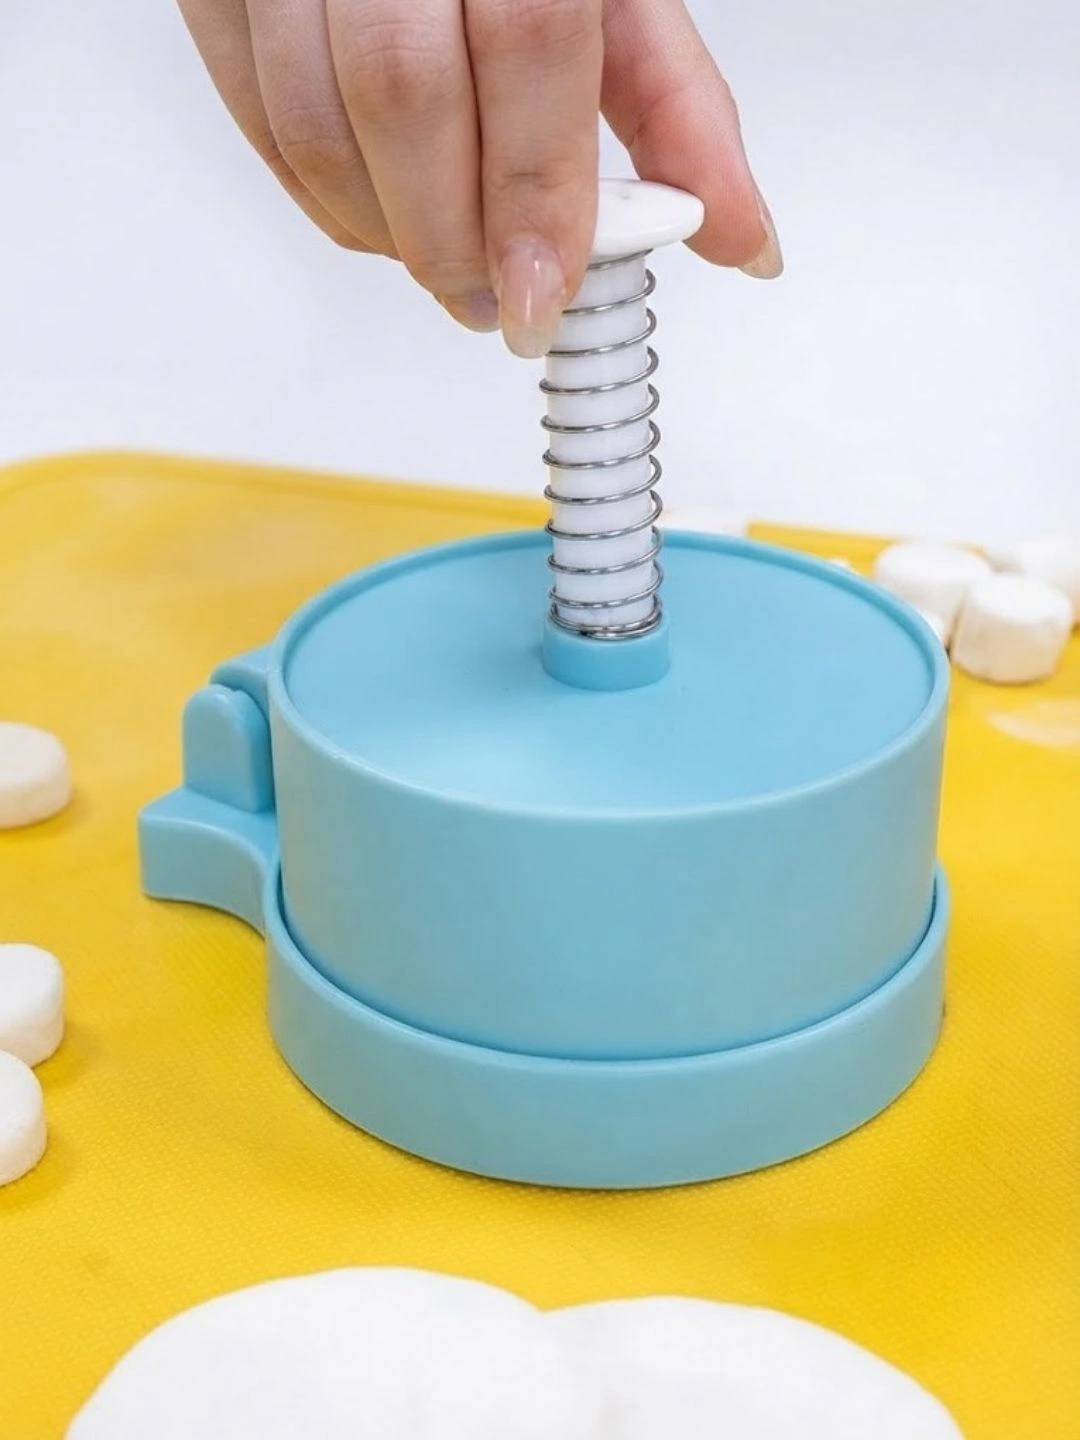
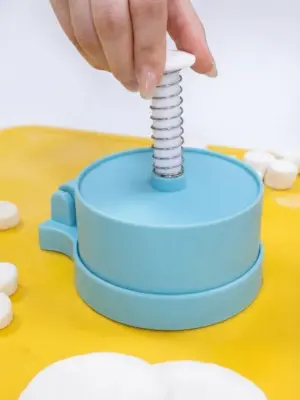
Manual Dumpling Skin Press and Maker Tool
₹49.00
Cash on Delivery Available | Limited Stock | Trending Style
Product Details:
- Product Type: Manual dough pressing tool and dumpling wrapper maker with a built-in spring mechanism.
- Design & Build: Compact sky-blue plastic body featuring a hinged pressing lid
- Quick Wrapper Pressing: Flattens dough balls into uniform, thin round sheets instantly with a single push.
- Multi-Purpose Food Utility: Ideal for shaping dumpling wrappers, momo skins.
- Non-Stick Surface: Smooth plastic molding prevents dough from sticking for clean and effortless removal.
- Compact & Easy to Use: Lightweight handheld design requires minimal effort.
The Manual Dumpling Skin Press and Maker Tool is a handy kitchen gadget designed to simplify making homemade dumplings and momos. Featuring a spring-loaded pressing mechanism and a smooth non-stick surface, it flattens dough balls into perfectly round, uniform wrappers in seconds. Complete with a hinged design and comfortable grip, this compact tool saves time and effort, making it a must-have for dumpling lovers.
Everyone in your friend circle probably has an opinion on ULIP plans, and most of it is outdated advice from a decade ago when charges were brutal and returns barely justified the lock-in. The market has actually changed a lot since IRDAI capped the charges, and today’s unit linked insurance plans are a genuinely different animal. You’re basically getting a life cover and a market-linked investment stitched into one product, so part of your premium buys you protection and the rest goes into equity or debt funds depending on how much risk you’re comfortable with.
The five-year lock-in period that people complain about is honestly a blessing in disguise. It stops you from panic-withdrawing the moment the market dips, which is exactly the kind of discipline most retail investors struggle with when they’re managing a regular mutual fund SIP on their own. Add to that the fact that maturity proceeds are usually tax-free under Section 10(10D), and long-term wealth creation through a ULIP starts looking a lot more attractive than people give it credit for.
Where people still go wrong is picking a plan based on the agent’s commission incentive rather than their own goals. If you’re 25 and saving for retirement thirty years away, an aggressive equity fund option inside your ULIP makes sense. If you’re closer to 50, shifting toward debt funds through the free switching option protects what you’ve already built. Always check the fund switch limit before you sign up, because unlimited free switches give you way more flexibility than a plan that charges you after four or five switches a year.
A few things trip people up when they buy this without reading the fine print. Death due to accident is covered, but death due to illness obviously isn’t, since that’s a separate category entirely. There’s usually a clear exclusion list too — accidents while intoxicated, self-inflicted injuries, or participation in dangerous sports like skydiving or scuba diving without proper certification typically won’t get you a payout.
| Size | 3XL, 4XL, L, M, S, XL, XS, XXL |
|---|
Leaving Comments
Leave a Comment
Related products
Reviews
There are no reviews yet.