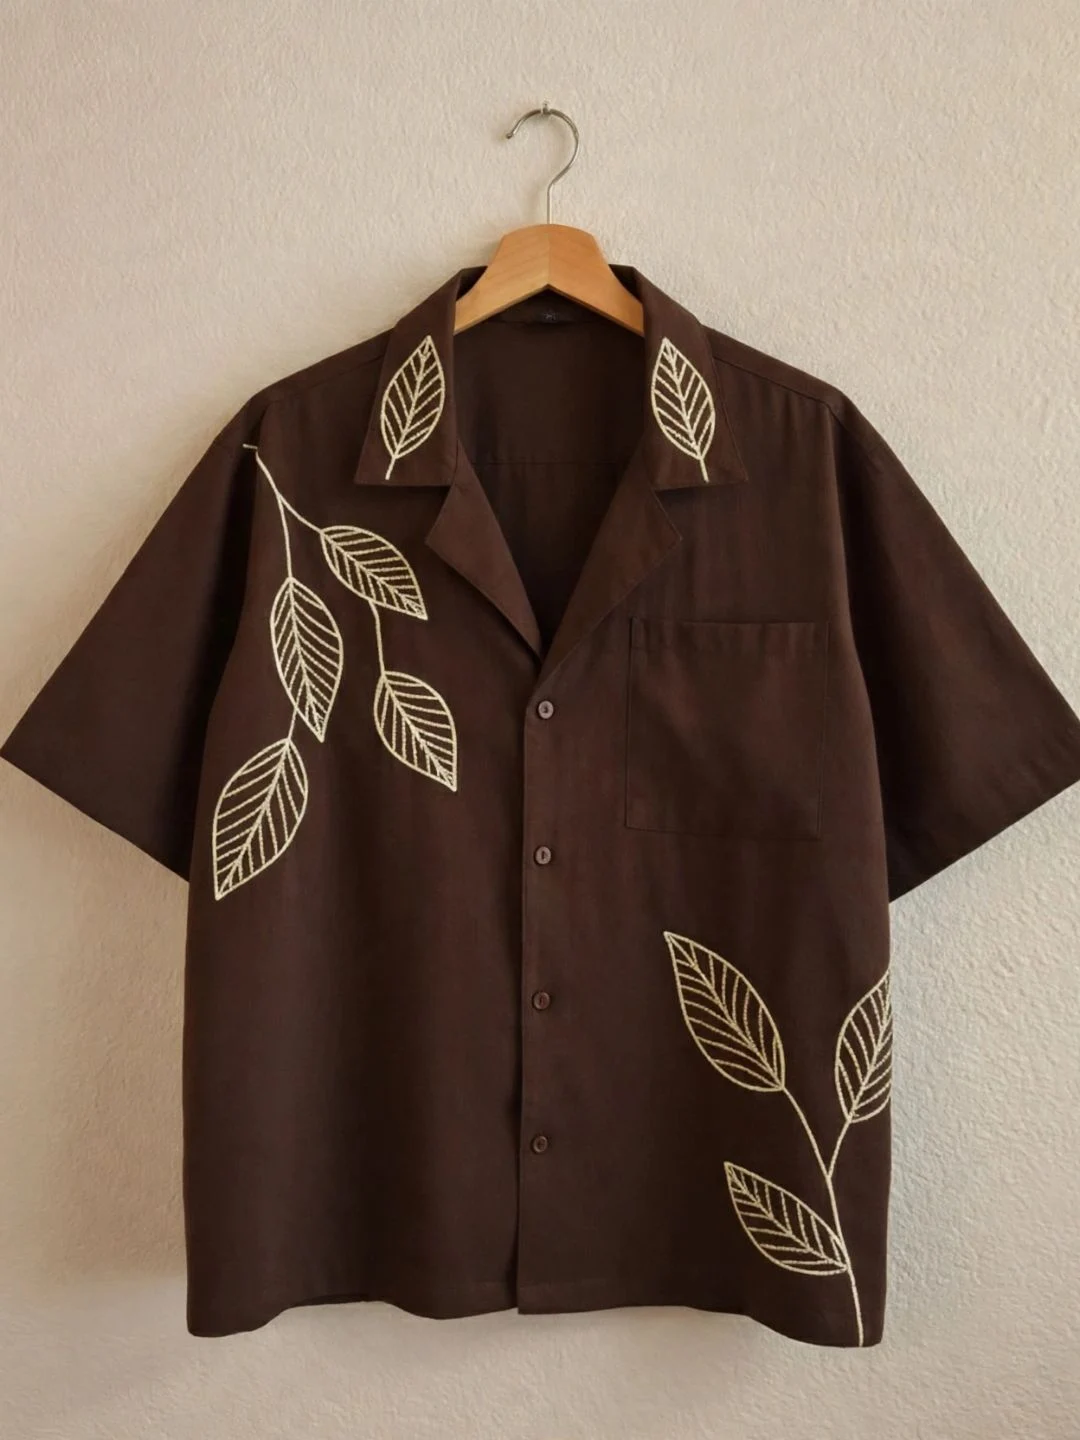
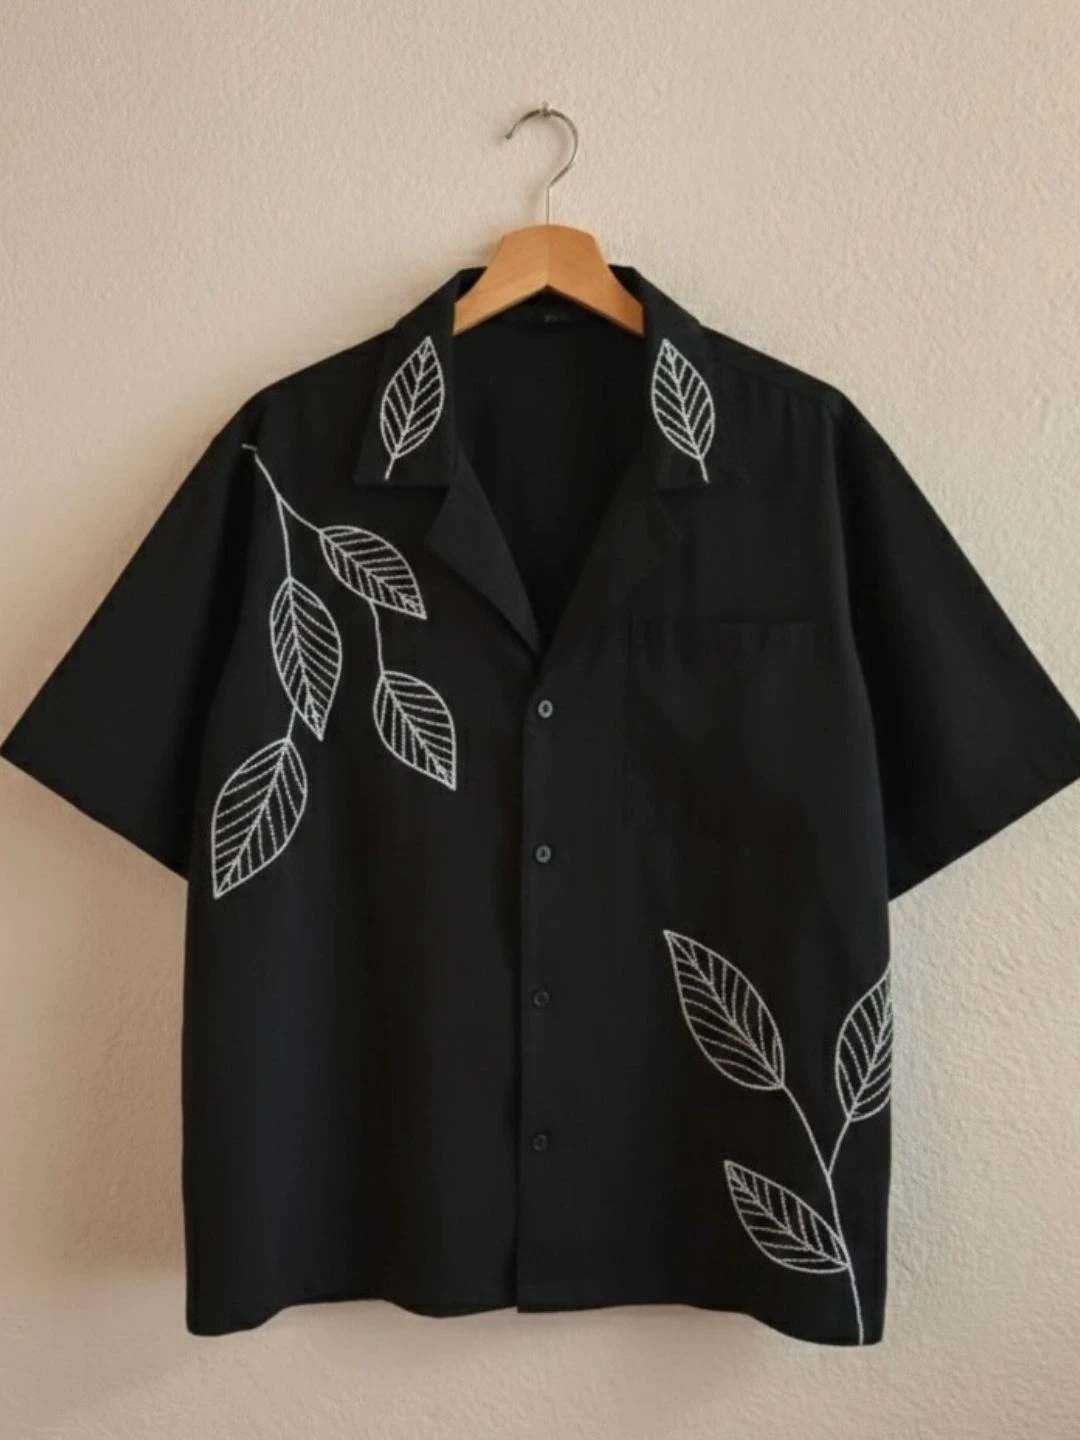
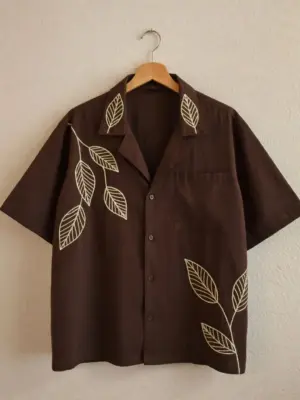
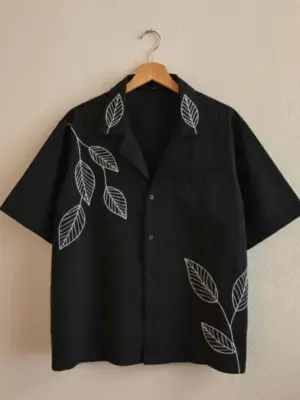
Botanical Embroidered Brown Cuban Collar Shirt
Original price was: ₹499.00.₹99.00Current price is: ₹99.00.
Cash on Delivery Available | Limited Stock | Trending Style
Product Details:
- Product Type: Men’s Short-Sleeve Casual Shirt
- Shirt Color: Deep Chocolate Brown with Contrast Cream Leaf Embroidery
- Sleeves: Short Sleeves
- Fit Type: Relaxed Resort Fit
- Collar Type: Classic Cuban / Camp Collar
- Fabric: Premium Breathable Cotton Linen Blend
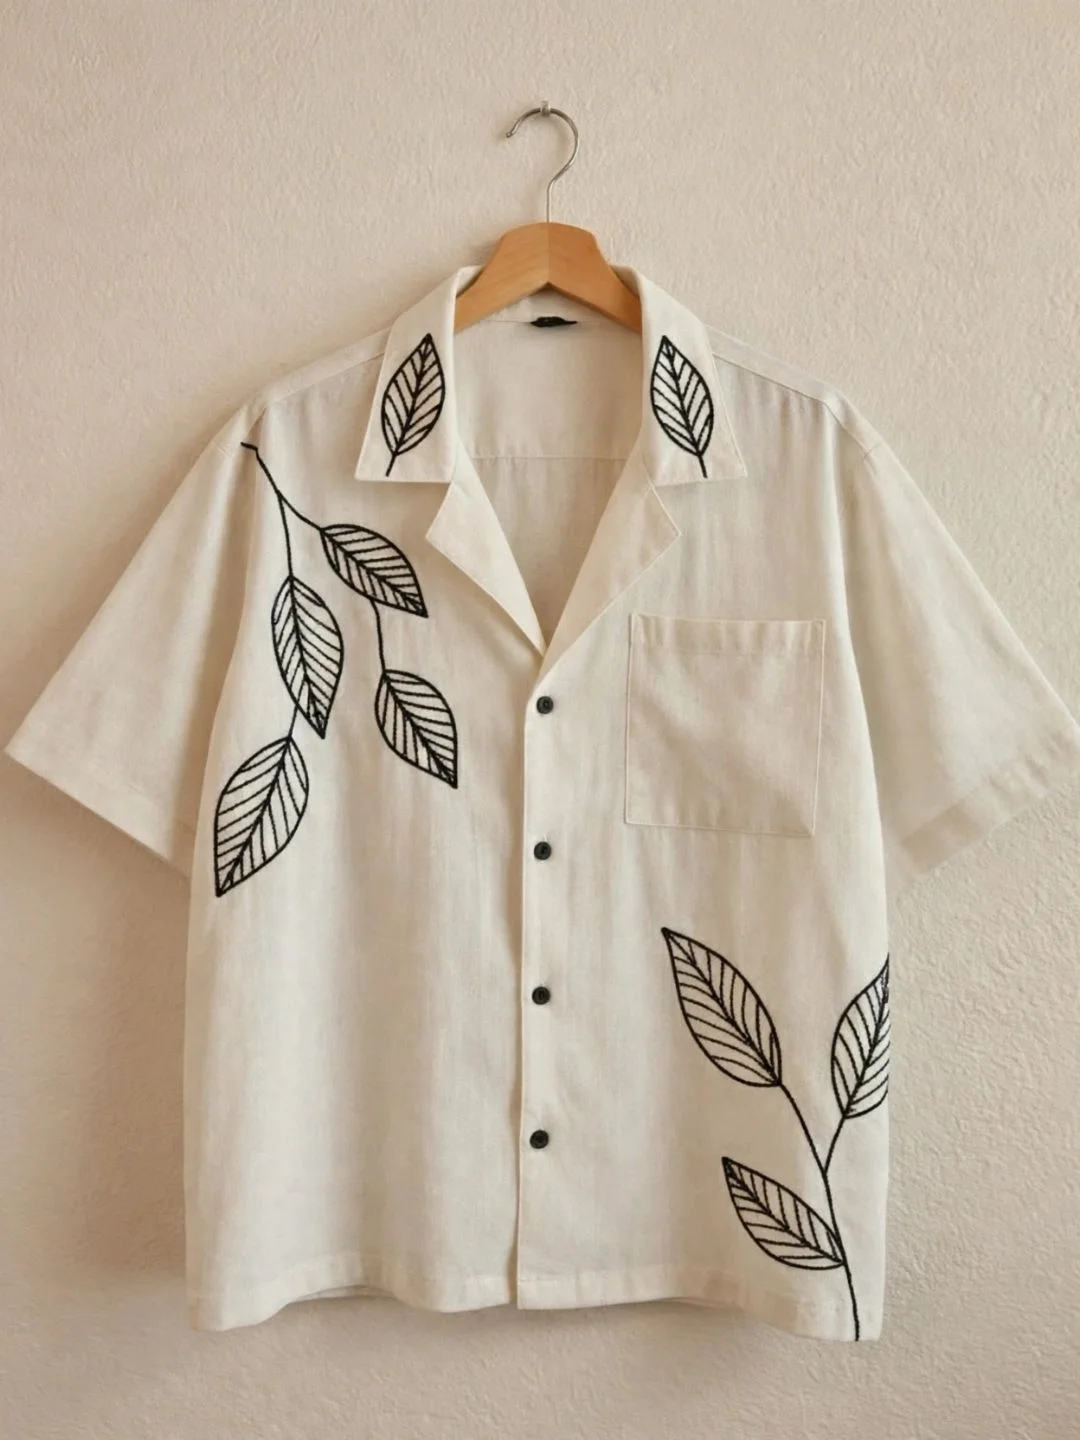
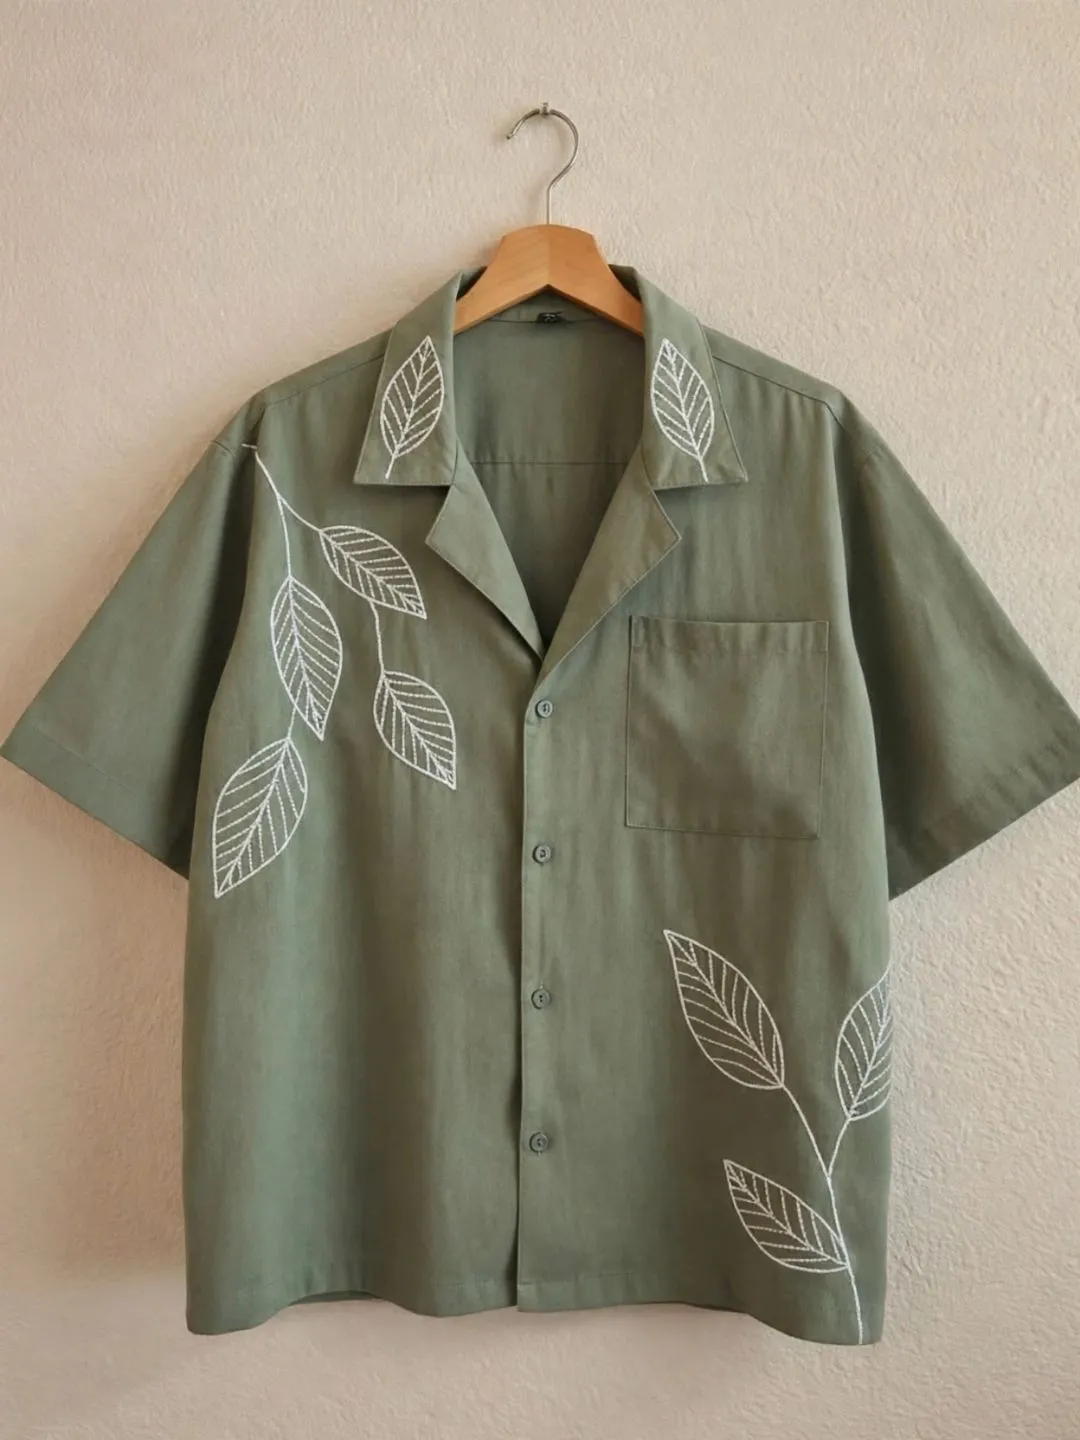
- Pattern: Solid Body with Intricate Hand-Style Vine and Leaf Embroidery Motifs
- Style: Tropical Chic / Bohemian Resort Wear / Artisan Casual
- Occasion: Summer Vacations, Beach Outings, Casual Brunches, Weekend Gatherings
Refresh your warm-weather rotation with this exceptionally stylish and meticulously detailed button-down shirt, featuring a rich chocolate brown short-sleeve camp-collar silhouette adorned with striking cream-colored embroidered vine and leaf motifs winding gracefully across the chest, collar, and lower front. Crafted from a soft, lightweight, and high-quality cotton-linen blend fabric, this standout garment guarantees supreme all-day comfort without ever compromising on a sharp, artisanal look.
There are really two things you’re insuring here, and people often only think about one of them. Structure cover protects the physical building itself against fire, storm damage, earthquakes, and similar structural risks. Contents cover protects everything inside — furniture, electronics, jewelry, appliances — against theft, fire, or damage. If you’re renting, structure cover isn’t your responsibility, but contents cover absolutely should be on your radar, especially if you own decent electronics or gadgets.
One number worth actually calculating properly is the sum insured. A lot of people just guess a round figure, but the right way to do it is based on the reconstruction cost of the house, not the market value, since insurers pay to rebuild the structure, not to cover the land value underneath it. Underinsuring here is a common mistake that only becomes obvious after a claim, when the payout falls way short of what it actually costs to rebuild.
Premiums for home insurance are honestly some of the lowest you’ll find relative to the coverage amount, often just a few thousand rupees a year for lakhs worth of protection. That low cost is exactly why so many homeowners never bother, assuming a disaster is unlikely enough to skip planning for. But floods, fires, and burglaries don’t check whether you were prepared, and the peace of mind from having a proper policy in place is worth far more than the small annual premium.
| Size | 3XL, 4XL, L, M, S, XL, XS, XXL |
|---|
Leaving Comments
Leave a Comment
Related products
Reviews
There are no reviews yet.