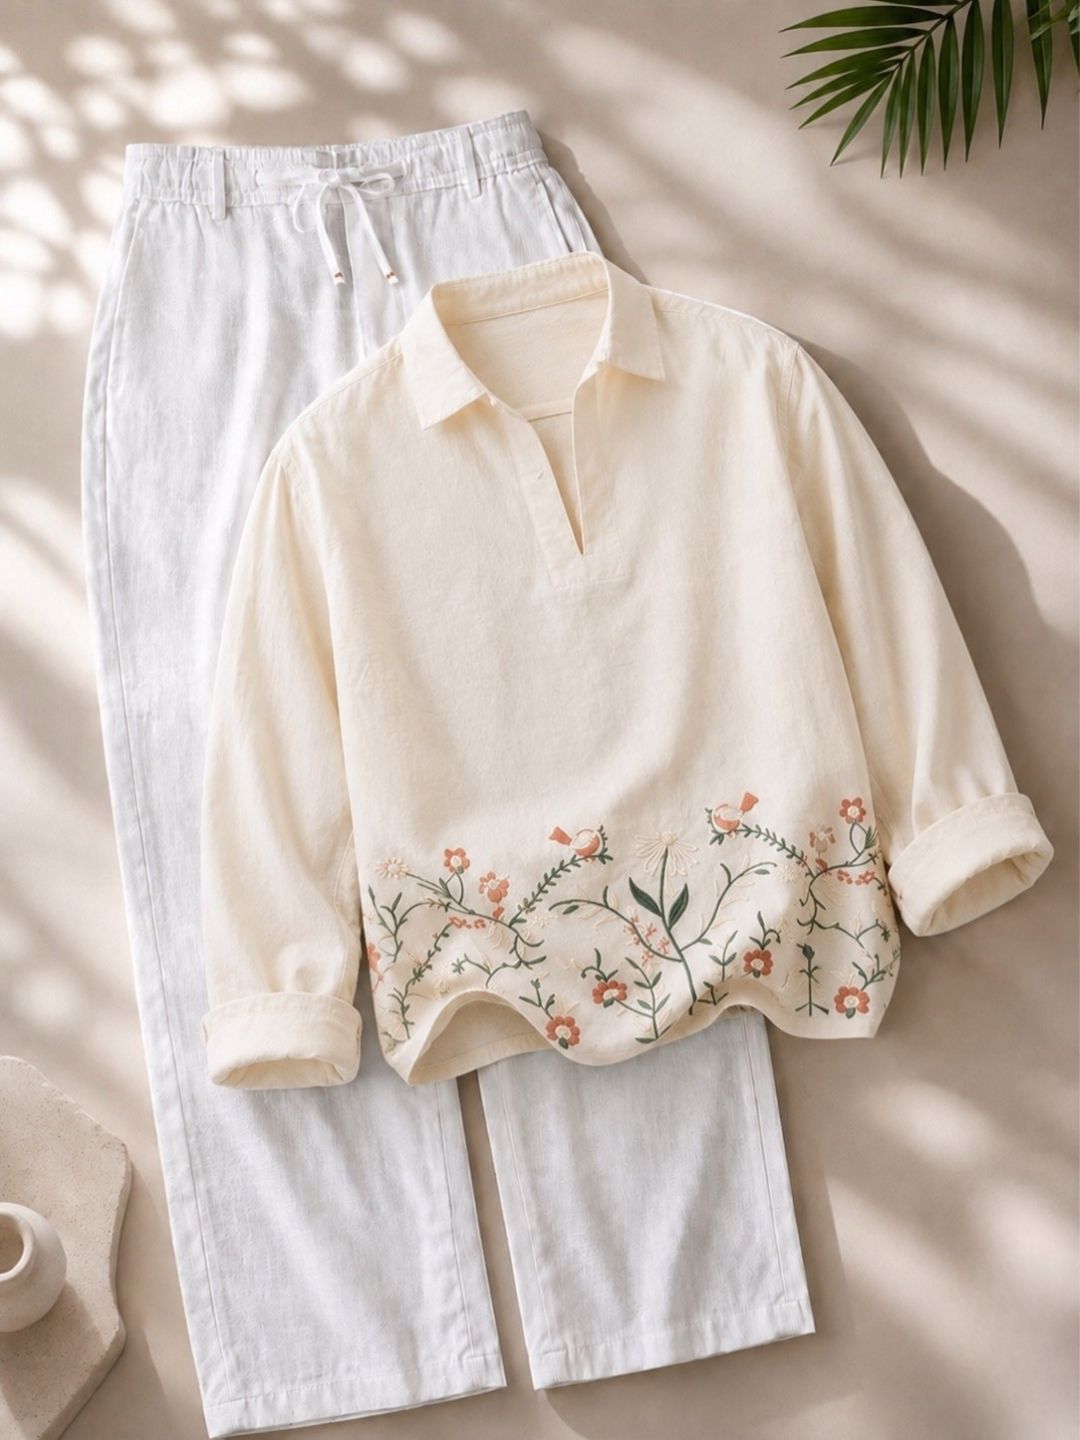
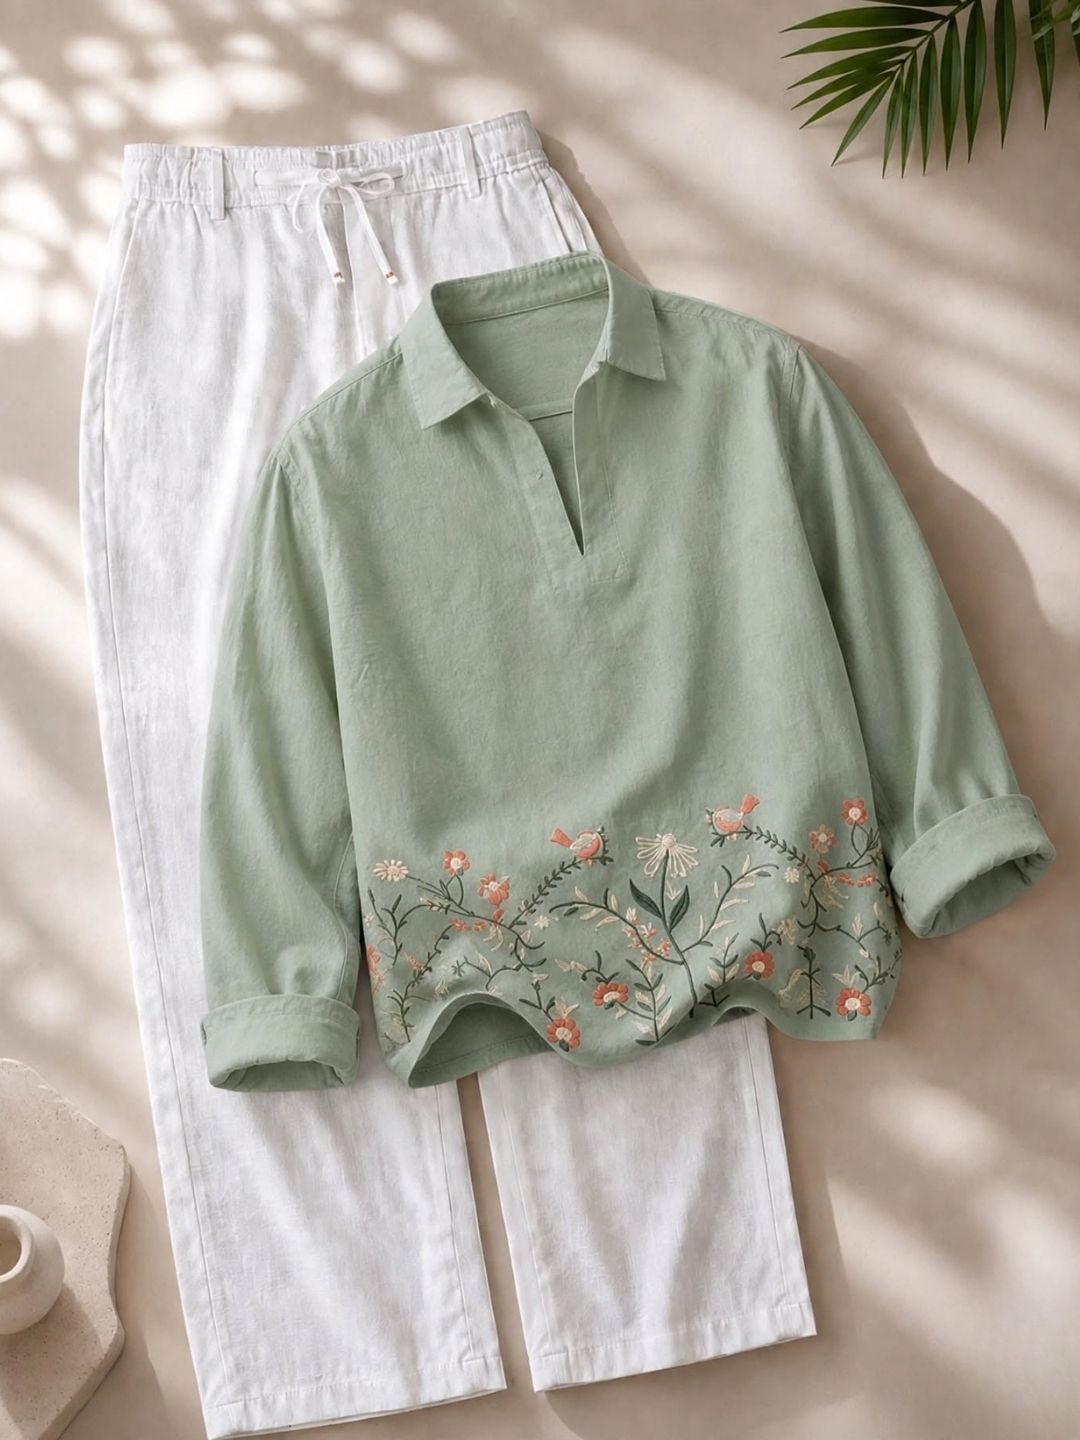
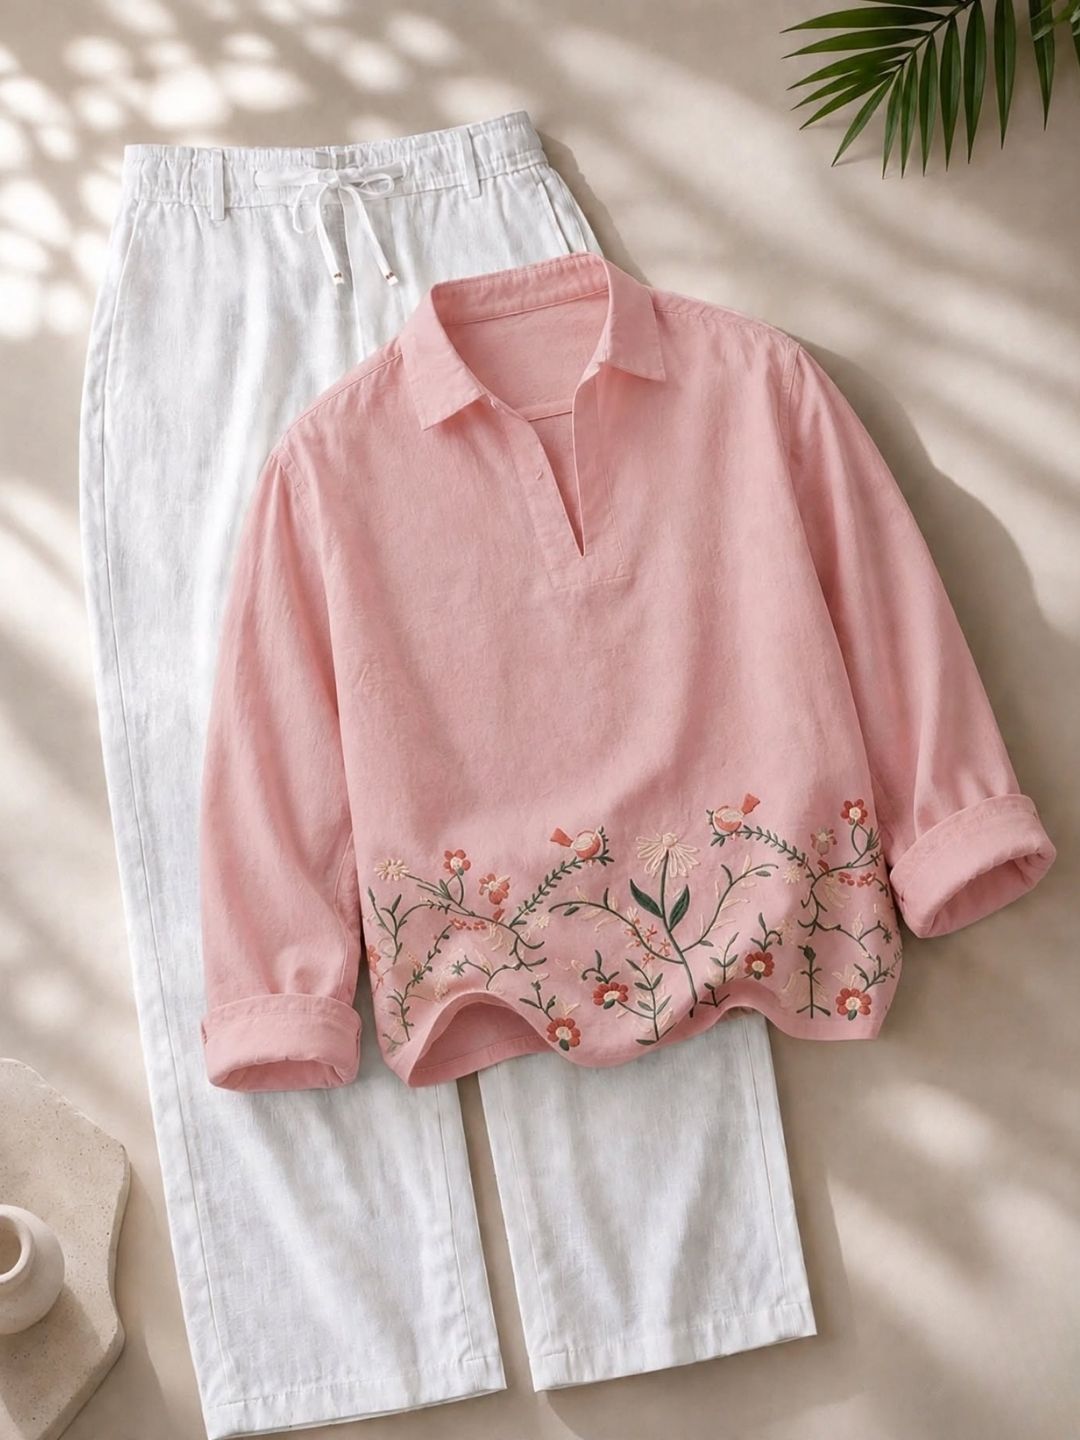
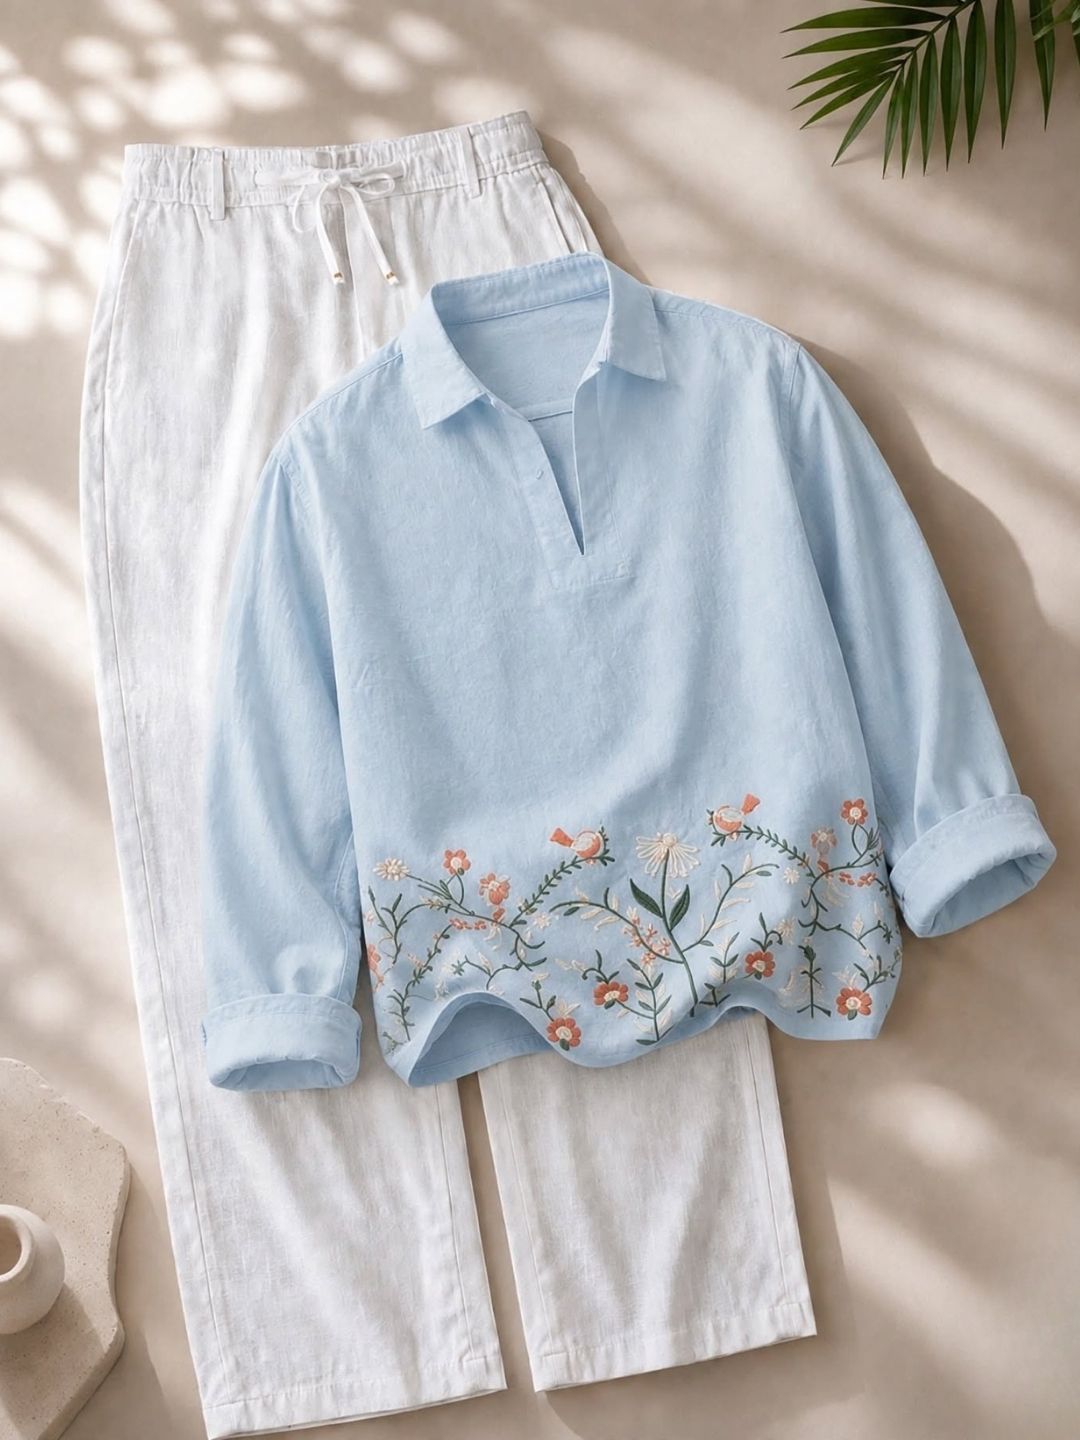
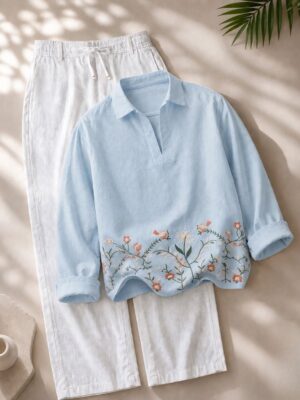
Floral Embroidered Cream Top and White Trouser Outfit Bundle
Original price was: ₹899.00.₹119.00Current price is: ₹119.00.
Cash on Delivery Available | Limited Stock | Trending Style
Product Details:
- Product Type: Women’s Shirt and Trousers Co-ord Set
- Shirt Color: Soft Cream with Multicolored Floral and Botanical Hem Embroidery
- Trousers Color: Crisp Pure White
- Sleeves: Full Sleeves with Folded Cuffs
- Fit Type: Relaxed Resort Fit
- Collar Type: Open V-Placket Spread Collar
- Fabric: Premium Breathable Linen Blend
- Pattern: Solid Upper Body with Detailed Nature-Inspired Floral Art Across the Lower Hem
- Style: Bohemian Casual / Resort Chic / Artisan Elegance
- Occasion: Beach Vacations, Summer Brunches, Casual Travel, Weekend Outings
Refresh your seasonal wardrobe rotation with this exceptionally stylish and meticulously coordinated two-piece ensemble, featuring a soft cream long-sleeve open-collar top adorned with charming floral and botanical embroidery along the lower hemline, paired seamlessly with clean white relaxed-fit trousers. Crafted from a soft, breathable, and high-quality fabric blend, this complete outfit guarantees supreme all-day comfort without ever compromising on a sharp, artisanal silhouette.
Buying health insurance for senior citizens after retirement is a completely different ballgame compared to buying it in your 30s, and pretending otherwise is where most families go wrong. Insurers price these policies based on age-related risk, so premiums are naturally higher, and a lot of plans come loaded with conditions that catch people off guard if they don’t read carefully before signing.
Co-payment clauses are probably the biggest surprise for first-time buyers. Many senior citizen policies require you to pay a fixed percentage of every claim out of pocket, sometimes 10-20%, regardless of how large the sum insured is. It’s the insurer’s way of managing risk on an age group that statistically files more claims, but it also means your actual out-of-pocket cost during a hospitalization can be higher than expected even with a solid policy in place.
Waiting periods are the other thing to watch closely. Most conditions common in older age, like cataracts, joint replacements, or pre-existing illnesses such as diabetes and hypertension, come with a waiting period before they’re covered, sometimes stretching to two or three years. If your parents already have a pre-existing condition, buying the policy earlier rather than later reduces how long that waiting period actually delays real coverage.
| Size | 3XL, 4XL, L, M, S, XL, XS, XXL |
|---|
Leaving Comments
Leave a Comment
Related products
Reviews
There are no reviews yet.